The Stories of John Fitzgerald Doe
16. The Deal He Almost Walked Away From
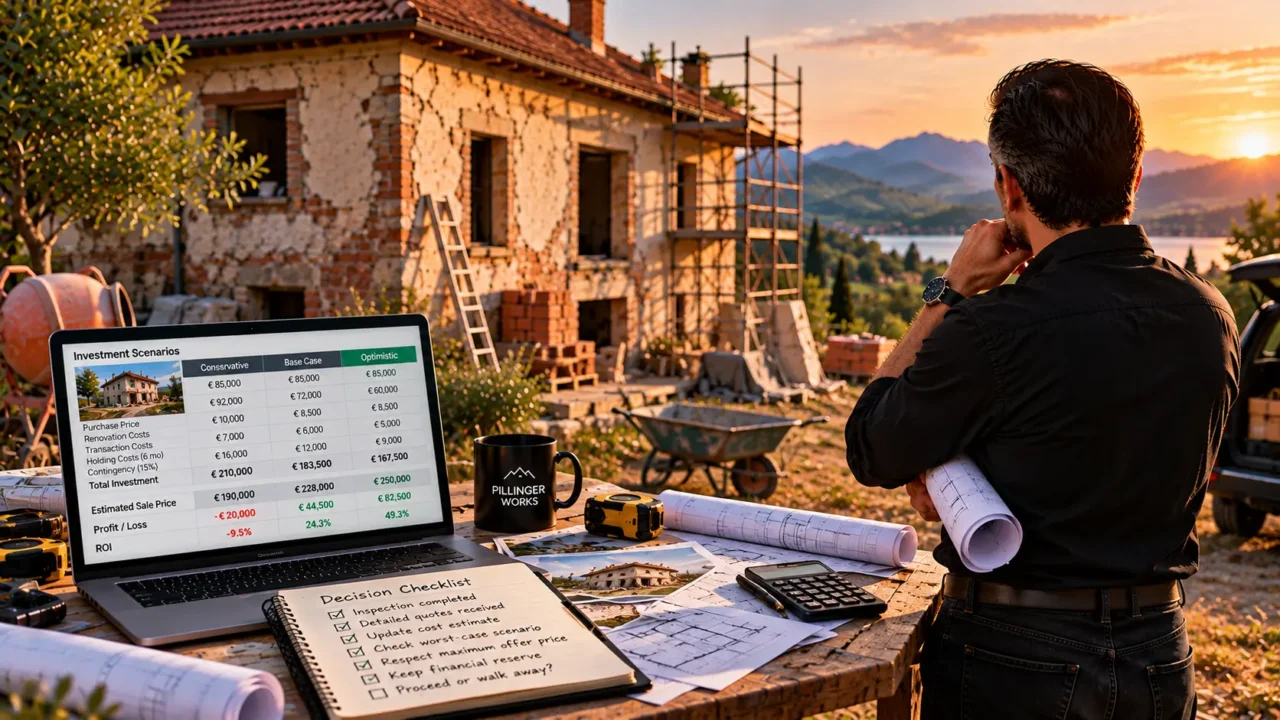
John had learned that a house did not become a good investment simply because it was listed cheaply. The asking price was only the first line of the story. The real question was what would be added to it—in money, time, and attention.
Over the previous weeks, he had gathered actual sale prices from the area, spoken with local professionals, and built three scenarios for the rural house. The most important figure was not the profit promised by the optimistic case. It was the maximum purchase price at which even the downside case would leave his reserves intact.
One question remained, and it could not be checked off in a spreadsheet: where was the damp coming from? The first inspection had revealed the symptom, not the cause. John therefore made no offer. Instead, he arranged for a specialist experienced in building diagnostics to inspect the property. Waiting irritated him. He could already picture the renovated house, and sometimes caught himself imagining the key turning in its front door.
On inspection day, the specialist examined the roof, gutters, base of the walls, and interior surfaces. The damp patch did not appear to have one dramatic cause. Poor rainwater drainage, inadequate damp protection, and several ageing details could be contributing together. The roof was also in no condition to be forgotten for years after a quick repair.
“That doesn’t mean the house can’t be saved,” the specialist said. “It means you shouldn’t guess the order of the work or its cost. Deal with the causes first. Make it pretty afterwards.”
The more detailed quotes arrived a few days later. The necessary work cost more than John’s earlier estimate. No single enormous item had wrecked the plan; several medium-sized costs had accumulated, and the contractors warned that further problems might emerge once work began. The project remained viable only if the seller accepted a substantially lower price.
John’s first reaction was unsettlingly familiar. He tried to rescue the original idea. The area might develop, he told himself; buyers would surely pay more for the renovated house; perhaps some of the work could be done more cheaply. Each thought contained a possibility—but none was new evidence.
The old John would probably have started rounding the costs down, the expected resale price up, and collecting reasons why he had to act now. This time, he noticed what was happening. He wasn’t looking for new information. He was looking for permission to keep wanting the deal.
He opened his spreadsheet and updated the figures using the professionals’ quotes. He did not use his contingency reserve to keep the project alive on paper; that money was there for unexpected events. The revised calculation put the purchase price below a clearly defined ceiling. If the seller would not accept it, the investment no longer met John’s own rules.
John did not try to persuade himself that the numbers would somehow improve. He calmly explained to the estate agent what offer he could responsibly make in light of the work identified and the remaining uncertainties. He did not threaten, rush, or raise the amount simply because he feared someone else might buy the house.
The seller’s response was clear: the offer was too low. For now, they were unwilling to reduce the price that far. John ended the call and stared at his spreadsheet for a few seconds. He was disappointed. He had already invested time, thought, and imagination in the property. Yet he also felt an unexpected sense of relief: he no longer had to argue against his own calculations.
He did not rule out another conversation later. The seller’s circumstances might change, new information might emerge, or the house might simply remain on the market. But John did not build his plan around that possibility. At that moment, the deal did not work at the offered price, so he did not raise his bid.
That same week, the stock market presented a situation that would once have pushed him to act immediately. A share price surged through a level he had been watching, and the chart seemed to show the start of the move he had been waiting for. John felt the familiar urgency: if he did not enter now, he would miss it.
But his entry rules were about more than price crossing a line. He needed confirmation of the breakout, and he needed to keep risk within the planned limits. The candle had already moved far beyond the point where his original plan called for an entry. Buying now would not be the same trade. It would be an attempt to chase the price after the fact.
John closed the order window. Not because he was certain the price would fall, but because his conditions had not been met. The stock rose again the next day. For a moment, he wondered whether he should have entered after all. Then he reminded himself: a sound decision does not become a bad one just because the price later moves favourably; nor would a poor decision be justified by a lucky outcome.
That evening, he wrote two lines in his journal. About the property: “I didn’t walk away from the deal. I walked away from the price at which it stopped being a good deal.” About the stock: “I didn’t miss a valid entry. There wasn’t a valid entry.”
He was still interested in the house. He continued watching the stock. But neither received a special exemption from his rules. John was beginning to understand that patience was not passivity, and decision discipline did not mean never feeling disappointed or rushed. It meant recognising those feelings without allowing them to make the decision for him.
Perhaps the property deal could still happen. Perhaps it would not. For once, John did not need an immediate answer. It was enough to know that his next move would be guided not by fear, hope, or the terror of missing out, but by the plan he had made with a clear head.
Academy connection: following rules, recognising emotionally driven decisions, and reviewing the plan.
This story is for educational purposes only and does not constitute investment or financial advice.