The Stories of John Fitzgerald Doe
15. The Loss He Should Have Budgeted For
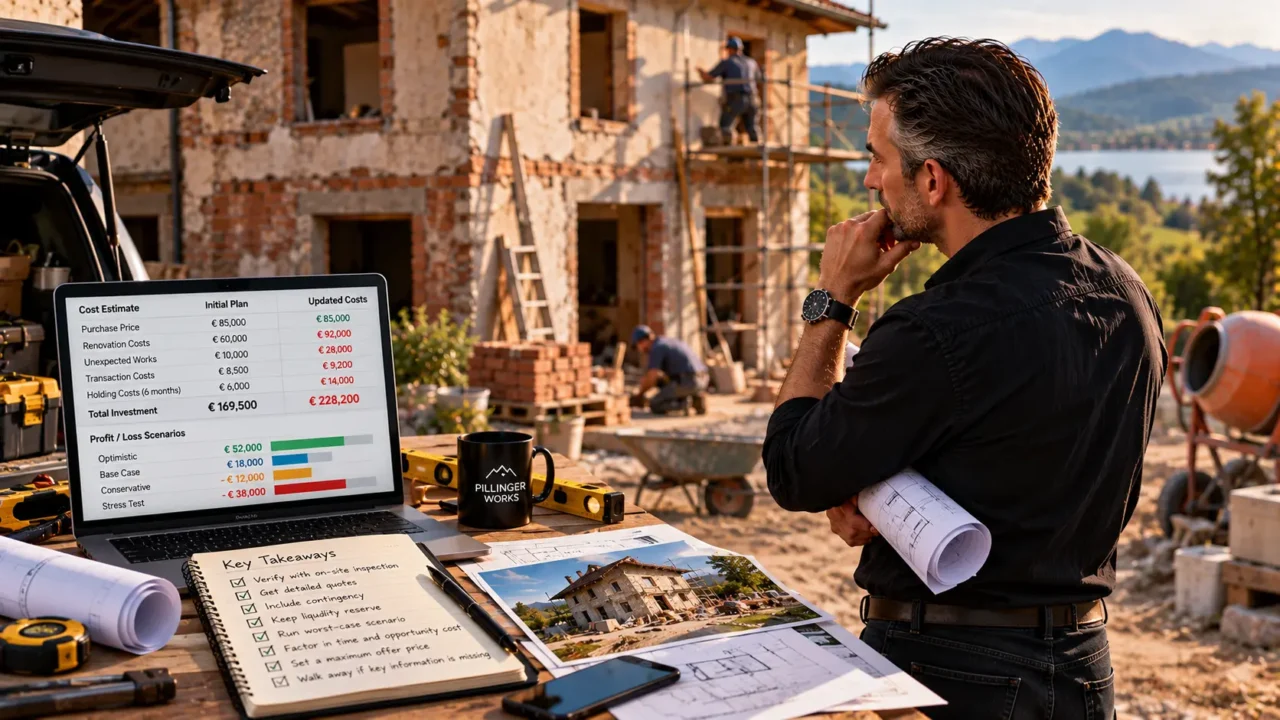
John Fitzgerald Doe did not make an offer on the house. Not yet. At the end of Episode 14, he already knew that the profit he had first imagined was only a rough sketch: after the viewing, the professional’s initial observations, and his research into the area, too many questions remained unanswered.
The following week, he tried to get answers to those questions. He wasn’t starting the calculation over; he was refining what he had already written down. He requested a more detailed estimate for the roof, arranged inspections of the electrical system and heating, and tried to establish what might be causing the damp patch on the wall.
He continued researching the local market, too. Listings had shown him what sellers were asking, but now he focused on completed sales. The two weren’t the same: an asking price did not prove that anyone had actually paid that amount for a property.
When the first more detailed estimates arrived, John wasn’t surprised that they were higher than his initial assumptions. What bothered him was that some costs could still only be expressed as a range. The cause of the damp, for example, needed further investigation, and until that was done, no one could reliably say what work would be required.
His earlier spreadsheet already included a contingency, but now he finally understood why he shouldn’t shrink that line just to make the result look better. The contingency wasn’t spare money he might be able to save. It was there to stop an unexpected defect from forcing the entire project into a series of bad decisions.
John built three scenarios from the information he had gathered. In the base case, the necessary work stayed close to the estimates and the sale wasn’t delayed much. In the less favorable case, repairs cost more, renovation ran late, and the house stayed on his hands longer. In the third, the damp pointed to a more serious structural issue, potentially requiring extra work and a much longer timeline.
He wasn’t claiming that the third scenario would definitely happen. He wanted to see how much pressure it would put on his finances if it did. The answer was uncomfortable: if he paid close to his maximum purchase price and renovation also exceeded the budget, he could quickly run out of room to maneuver.
John recognized the feeling from trading. He didn’t choose a position size only by asking how much he could make in the best-case scenario; he also considered whether he could withstand an unfavorable outcome. Now he was trying to apply the same principle to property—with one important difference: there was no single stop-loss level that would close the problem.
In a renovation, costs can compound. If roof work is delayed, interior work may be delayed as well. If another defect appears during demolition, both cost and time can increase. And if the house doesn’t sell when planned, holding costs keep accumulating while the money remains tied up in the property.
So John separated two things. One was the project’s budget, including a contingency for renovation. The other was the liquid reserve he wanted to keep outside the project. He didn’t want to put all his readily accessible savings into the house and then hope nothing went wrong.
He recalculated his potential offer price. Not by forcing the projected profit to reach his preferred target, but by checking whether the project could remain manageable even in a less favorable scenario. If the seller wouldn’t accept an offer at that level, it didn’t mean John had to bid higher. It might simply mean the house wasn’t a good investment on his terms.
At first, the idea felt strange. John had once imagined that a good investor spotted an opportunity and seized it. Now he was beginning to understand that a good investor also had to recognize when the price was wrong, uncertainty was too high, or a project might endanger other financial goals.
He still had no definitive answer about the cause of the damp. So he decided not to make an offer without further professional investigation. He wouldn’t replace missing information with an optimistic assumption, or confuse his enthusiasm for the house with evidence that the numbers supported buying it.
That evening, he opened his Trading Journal again. His trading records had already taught him that good risk management didn’t mean never losing. It meant that one bad outcome shouldn’t endanger the entire system. Sitting over the property spreadsheet, he tried to keep the same principle in mind.
The house’s future was still undecided. John could still see potential in it, but he no longer wanted it at any cost. First, he wanted to know how much loss he could withstand, how much capital would be tied up, and whether he would still have room to maneuver if things didn’t go according to plan.
He couldn’t remove risk from the project. But he could decide whether to take it blindly or prepare for it in advance.
What can we take away from John’s story?
• The cost planning begun in Episode 14 is only a starting point. Estimates need to be refined with on-site inspections, detailed quotes, and verifiable market data.
• The project budget should include a contingency for unexpected work, while an adequate liquid reserve should remain outside the project as well.
• An unfavorable scenario is not a prediction; it is a stress test showing whether the investor can withstand several things going wrong at once.
• A stock-market stop-loss and a property contingency are not the same. During renovation, problems can compound, and time matters as much as cost.
• Set a maximum offer based not only on potential profit, but also on possible loss, tied-up capital, and liquidity.
• When important information is missing, further inspection—or walking away from the deal—is part of risk management.
Educational fiction only; not investment, property-purchase, or tax advice. Renovation costs and property-market outcomes are uncertain; specific decisions require appropriate professional inspection.