The Stories of John Fitzgerald Doe
13. The Numbers That Didn’t Tell Him What He Wanted to Hear
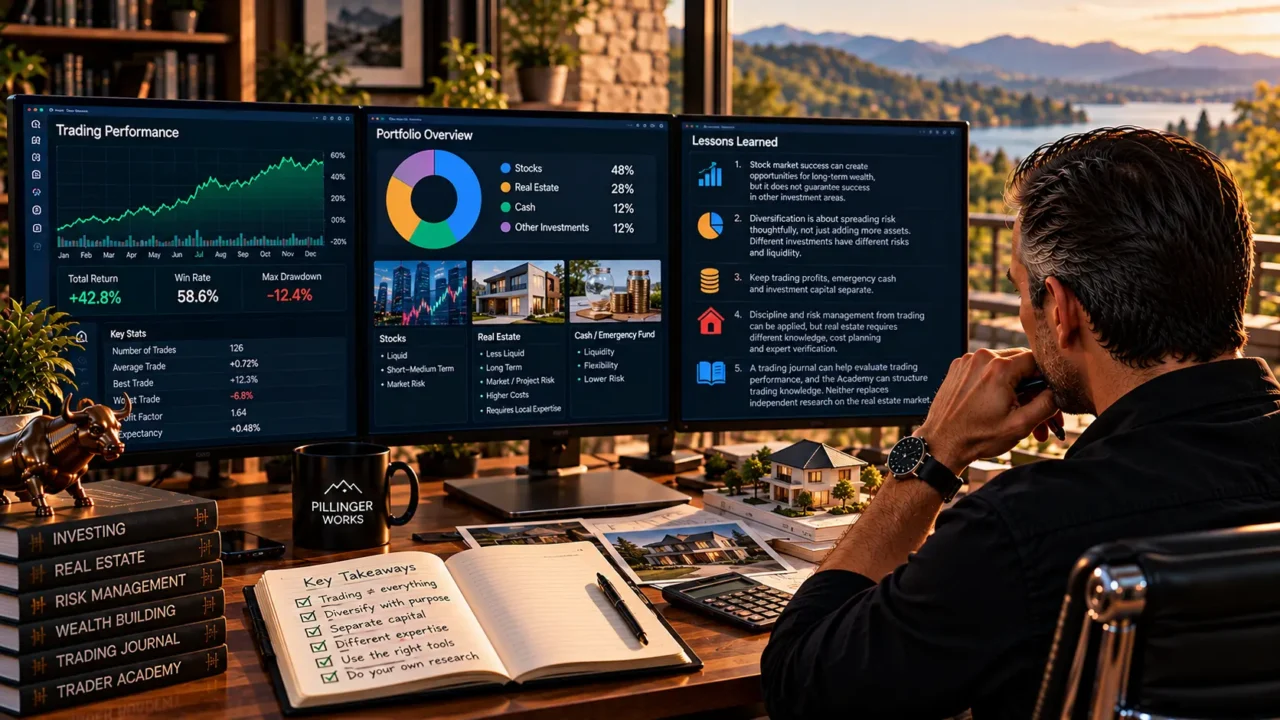
Lately, John Fitzgerald Doe had less and less of that feeling that he had to do something in the market at all costs.
That alone was a major change. A few months earlier, even a quiet trading day could leave him feeling as though he had missed something. Now he could close the charts when no suitable opportunity appeared. He wasn’t patient every moment of every day, but he was getting better at recognizing when boredom was disguising itself as a trading decision.
Overall, his trading had been going well. The results weren’t down to one lucky trade; they reflected months of work, more consistent use of his rules, and a few important lessons. Profit was slowly becoming more than a number in his account. It was beginning to change how he thought about his future.
One evening, he reviewed his statements and his Trading Journal. One summary looked particularly good at first. His eyes went straight to a handful of standout trades he still remembered with pride. He could almost hear his old thought: “Looks like I finally understand how this works.”
Then he went back and looked at the full period.
Alongside the winning trades were losses, missed opportunities, positions he had once closed too early, and decisions that had made money even though they hadn’t followed his plan. The full picture didn’t erase his results. It simply gave them more nuance.
John now knew that one good trade could not, by itself, prove that a strategy worked. But he also understood that a few disappointing trades didn’t necessarily invalidate an entire method. The question was what the data showed across a sufficiently large sample, and how consistently he had followed his own rules.
So he looked at more than profit in his Trading Journal. He compared entry conditions, exits, position sizes, and market environments. He tried to separate the quality of a decision from the randomness of its outcome. Not every question had a clear answer, but his questions were becoming more precise.
The numbers gave him reason to be pleased. His trading profits had grown to an amount he no longer wanted to keep putting entirely back into the same activity, again and again. It wasn’t that he had lost faith in the stock market. Quite the opposite: he took what he had achieved seriously, and began thinking about how to turn it into more resilient long-term wealth.
The idea first appeared almost in passing. During a conversation with a friend, someone mentioned an inexpensive house in need of renovation in a rural village. John didn’t know the property, and he didn’t immediately start running the numbers. But on the way home, he caught himself returning to the same question: alongside his stock-market investments, would it make sense to put some money into a completely different kind of asset?
He wasn’t looking to replace trading. He wanted to understand how he might spread his wealth across different types of investments. Stocks were liquid, their prices changed every day, and he had already built a system for making decisions about them. Property worked differently: it was harder to sell quickly, required substantial capital upfront, and renovation or maintenance would bring tasks he didn’t yet have enough experience to handle.
John knew that “diversification” was a good-sounding word, but not a magic spell. A property wouldn’t automatically reduce every risk he faced, and profits made in the stock market wouldn’t make a property deal a good investment by default. The real question was whether this new asset would fit his goals, financial capacity, and available time.
So he didn’t start by searching for houses. He started by writing down questions. How much could he set aside while still keeping a liquid reserve? What costs would come on top of the purchase price? What would make a rural area genuinely promising, rather than merely appear so? How much renovation risk would he be willing to take? And what if the resale took far longer than expected?
Then he reviewed his trading data again. Not to ask it for permission to make a new investment, but to remind himself that past results were no guarantee of future performance. His trading experience could give him discipline and a framework for thinking about risk, but he would have to learn the property market separately.
John closed his laptop, and for once he didn’t feel that he had to find the next big opportunity immediately. Instead, he felt curious. Perhaps the next stage of building wealth wouldn’t begin with another trading strategy, but with learning to ask good questions in a different world.
The rural house was still just a passing mention in a conversation. There was no offer, no deal, and no profit that could be booked in advance. But a new plan had taken shape in John’s mind: not necessarily to take more risk, but to build more deliberately on what he already had.
The following week, he opened a blank document and typed at the top: “Investments beyond the stock market — what do I need to learn before deciding?” This time, he didn’t rush to find the answers.
What can we take away from John’s story?
• Strong trading results may create opportunities for long-term wealth building, but they do not guarantee success in another investment area.
• Diversification is about deliberately spreading risk, not simply adding more assets to a portfolio. Different investments can have very different risks and liquidity.
• Profits, liquid reserves, and capital genuinely available for investment should be treated separately.
• Trading experience can transfer discipline and a risk-aware mindset, but buying, renovating, and selling property require separate market knowledge, cost planning, and professional inspection.
• A Trading Journal can help evaluate trading performance, while the Academy can organize trading knowledge. Neither replaces independent research into the property market.
Educational fiction only; not investment, property-purchase, or tax advice. Investments involve risk, and past performance does not guarantee future results.